Throughout the artificial intelligence (AI) revolution, Palantir Technologies (PLTR +1.09%) has been one of the most polarizing stocks. One camp sees a unique software company that actually integrates AI into messy operations. The other views Palantir as nothing more than a consulting firm.
With Palantir stock trading around $174, investors may be wondering what the business could look like a year from now, and what price it would reasonably support.
Let’s take a look at the company’s most recent quarterly results and assess some of its new partnerships to help discern how Palantir is trying to sell more than data analytics. From there, valuation analysis can shape whether the next 12 months look more like a grind or upside.
Image source: The Motley Fool.
Palantir is firing on all cylinders
Palantir’s second-quarter earnings were more than a polite beat. Total revenue reached $1.9 billion, up 93% from a year earlier and 19% sequentially. U.S. commercial revenue rose 149% year over year to $764 million, while U.S. government revenue increased 90% to $809 million.
This split is important to keep an eye on because Palantir’s commercial segment is on pace to overtake the government book if current trends hold. This is meaningful, as it underscores Palantir’s ability to expand beyond its roots in the public sector and penetrate an intense enterprise software market in the private sector.
Management raised full-year revenue guidance to about $8.2 billion, or 82% growth. The catalyst behind the acceleration stems from the U.S. commercial business, which is guided to grow at least 134% to $3.4 billion.
That bull thesis is straightforward: Customers are not just trying Palantir’s software. They are buying it, signing multiyear agreements, and expanding use cases across the platform.

Today’s Change
(1.09%) $1.90
Current Price
$176.24
Key Data Points
Market Cap
Day’s Range
$172.61 – $177.88
52wk Range
$106.37 – $207.52
Volume
60.1K
Avg Vol
39.6M
Gross Margin
84.80%
How Palantir is expanding beyond its core suite
For years, Palantir looked like an expensive enterprise software suite with a government accent. But its newer pitch is a sovereign AI stack that helps keep data, models, and operational know-how inside the customer’s walls instead of being vulnerable to an external model.
For starters, Palantir is pairing its Artificial Intelligence Platform (AIP) and Foundry suites to open models on Nvidia Nemotron so agencies and infrastructure operators can run and train models in classified environments. This is not just another chatbot from a large language model (LLM). Palantir is giving customers the ability to hone generative models with their own data without requiring them to hand anything proprietary to a frontier lab.
On the compute side, Palantir is collaborating with Nebius Group. As Palantir’s preferred sovereign AI infrastructure partner, Nebius’ capacity and inference will now sit inside Palantir’s perimeter. This means customers can run open models on Nebius’ cloud while Palantir’s AI operating system handles the authorization, isolation, and operational layer that allows companies to retain control over their proprietary data.
Taken together, Nebius and Nvidia are helping Palantir expand its total addressable market (TAM) beyond pure-play software. While the company still sells a software suite — Foundry, Apollo, and Gotham — AI infrastructure is helping Palantir market its capabilities beyond selling incremental licenses and professional services.
Where could Palantir stock be trading in one year?
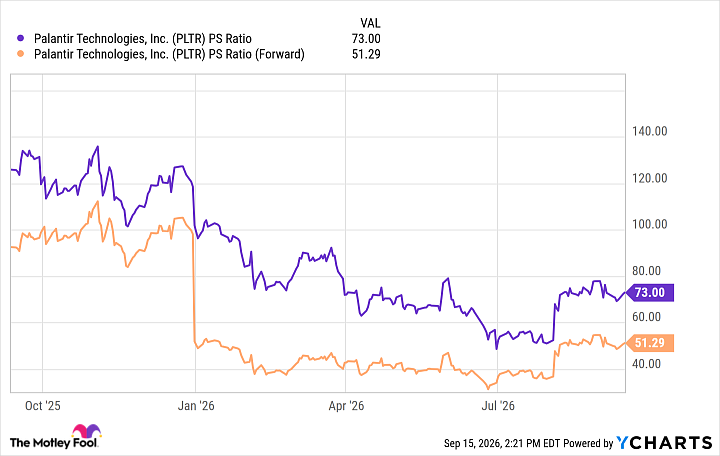
Palantir’s stock price already bakes in a lot of optimism. The company’s trailing-12-month price-to-sales (P/S) ratio hovers around 73 while its forward P/S multiple sits around 50. Wall Street’s consensus 2027 revenue estimate clusters around $12.2 billion, which would be about 50% growth after this year’s expected performance.
PLTR PS Ratio data by YCharts
If I assume Palantir’s P/S ratio compresses as growth cools, it could land somewhere in the 38 to 45 range. Indeed, this is still rich for software, but far less extreme than where Palantir trades today. This range points to a market cap between $464 billion and $550 billion based on next year’s revenue forecast. At the high end, this implies 31% upside from Palantir’s current level. On a per-share basis, that would put Palantir stock around $230.
While the operating trends imply the company is executing, valuation multiples say you’re paying a premium for that execution. With that said, if commercial growth rates remain high and sovereign deployments turn into a new, durable revenue stream, Palantir stock can still carry meaningful upside from here. While it’s not a bargain, I see Palantir as a compelling name to buy and hold outside the usual AI stocks across chips, memory, and hyperscaler clouds.