Joby Aviation (JOBY -1.47%) and Archer Aviation (ACHR -3.66%) are both early movers in the nascent electric vertical take-off and landing (eVTOL) aircraft market. But over the past 12 months, shares of Joby and Archer have declined about 60% and 40%, respectively.
Without the Federal Aviation Administration’s (FAA) certification for their first commercial flights, both companies struggled to impress their investors. Geopolitical conflicts, inflation, and fears of interest rate hikes also drove many investors toward more conservative investments.
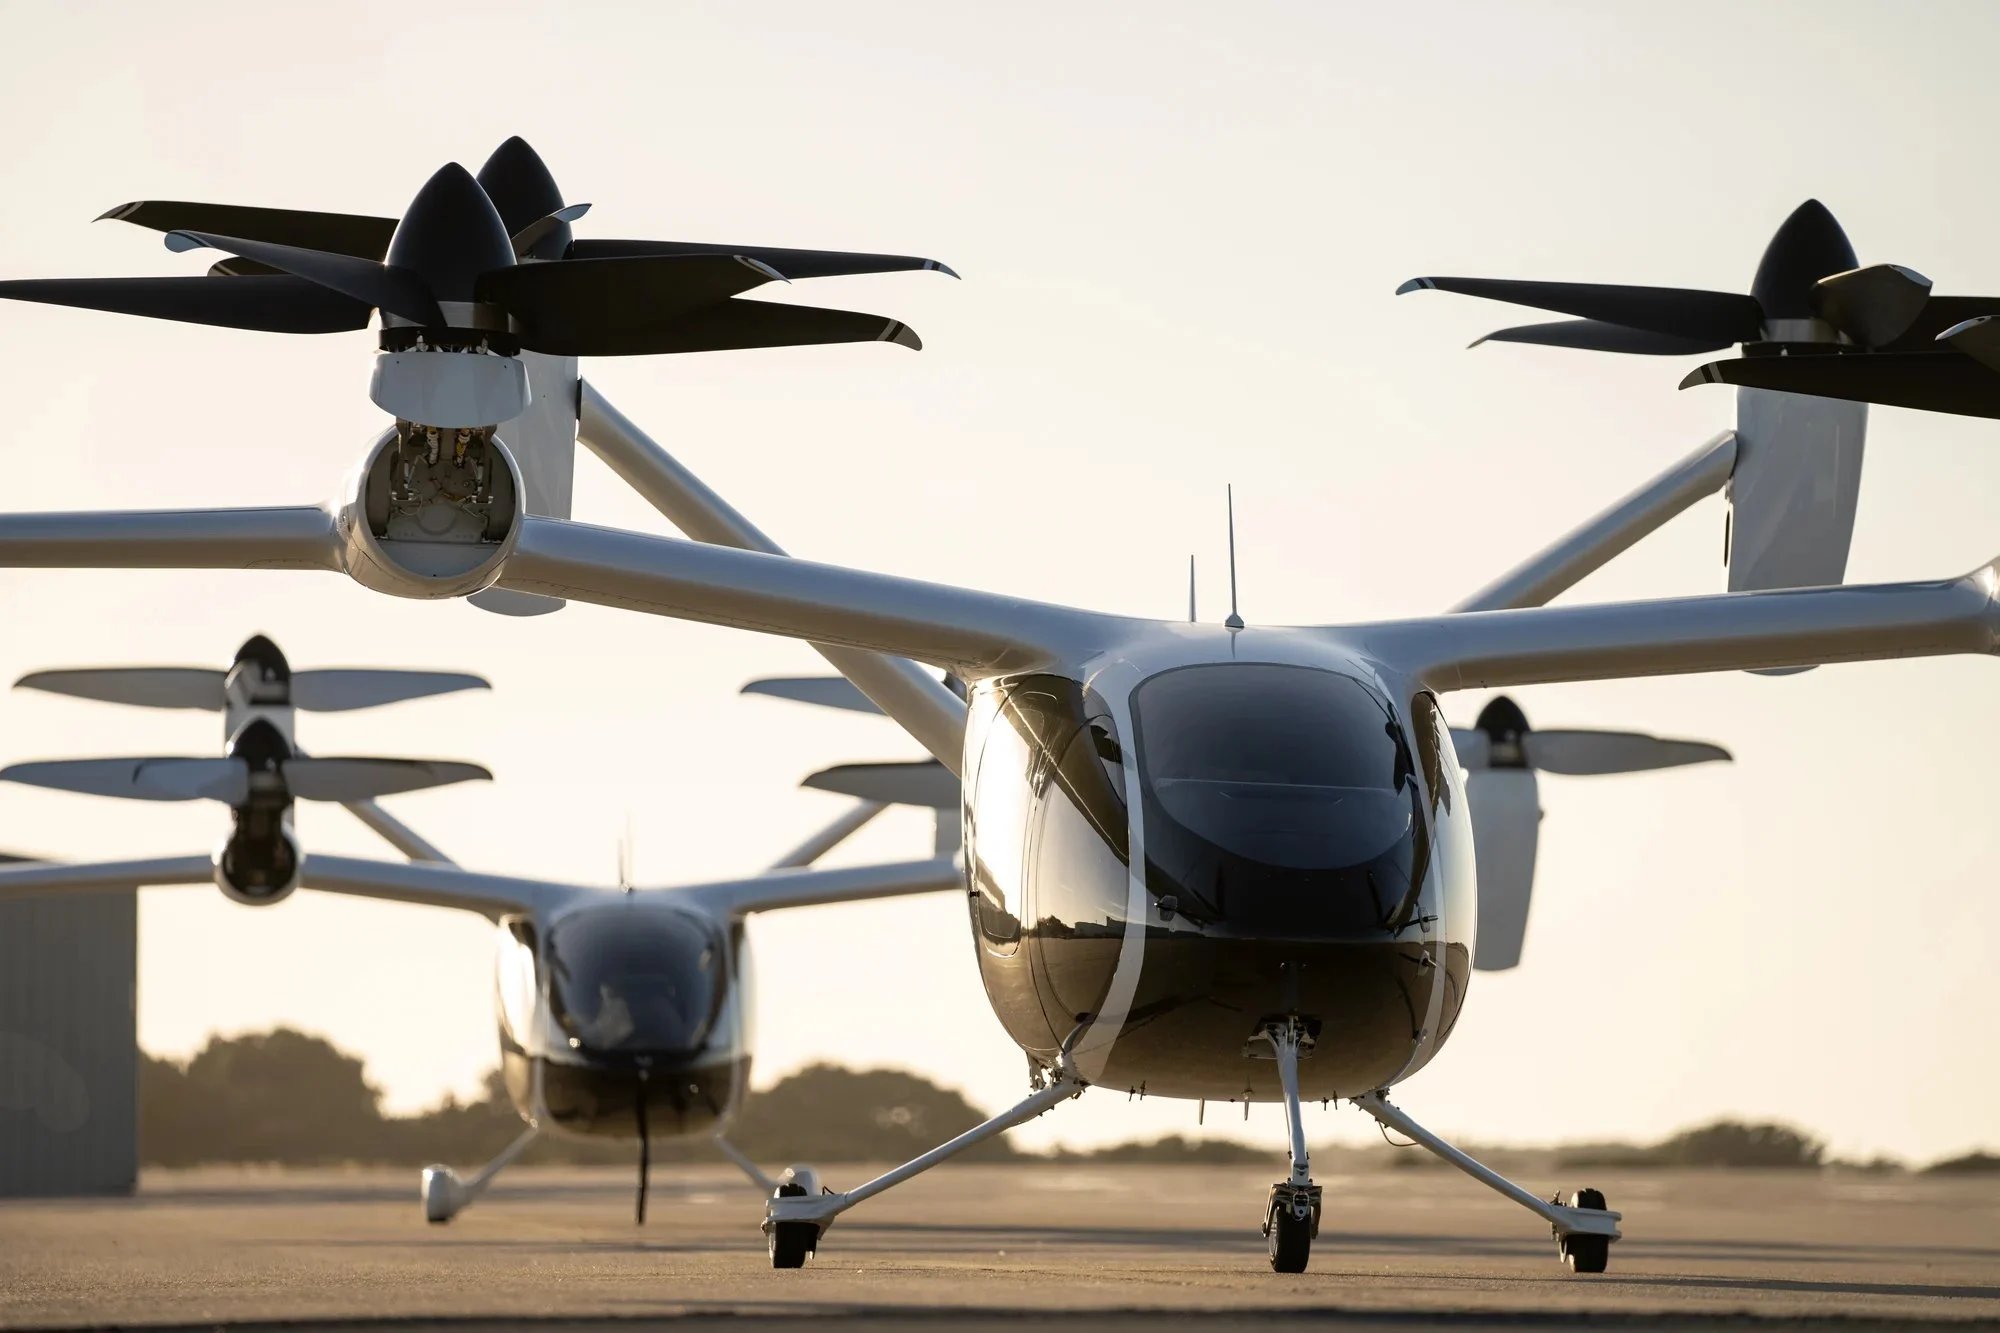
Image source: Joby Aviation.
But if we take a closer look at Joby and Archer, we’ll notice that one key metric sets the two companies apart. With a market cap of $6.1 billion, Joby trades at 51 times this year’s sales. Archer, which is valued at $4.2 billion, trades at 278 times this year’s sales. Let’s see why Archer’s price-to-sales ratio is so much higher than Joby’s, and if that will change in the future.
Joby generates much more revenue than Archer
Neither Joby nor Archer generates any revenue from commercial eVTOL flights. However, Joby’s revenue surged from less than $1 million in 2024 to $53.4 million in 2025 as it received the first payments from its contracts with the U.S. Air Force’s Agility Prime program. It also recognized some revenue from its acquisition of Blade Air Mobility‘s passenger business, a provider of helicopter and seaplane services, which closed last August.
For 2026, analysts expect its revenue to more than double to $119.5 million as it integrates Blade’s passenger business and generates more revenue from its Agility Prime R&D contracts.

Today’s Change
(-1.47%) $-0.09
Current Price
$6.04
Key Data Points
Market Cap
Day’s Range
$6.04 – $6.17
52wk Range
$6.04 – $19.98
Volume
10M
Avg Vol
38.7M
Gross Margin
-365.45%
Archer also holds contracts with the Agility Prime program, but they function more like government-subsidized test flights rather than revenue-generating R&D projects. Unlike Joby, which plans to become a vertically integrated “transportation as a service” business that manufactures, owns, and operates its own air taxi network, Archer is an original equipment manufacturer (OEM) that sells most of its aircraft to third-party fleets. That’s why it hasn’t acquired any consumer-facing, revenue-generating businesses.
Archer generated less than $1 million in revenue in 2025. Still, analysts expect that figure to rise to $15.1 million in 2026 as it collects more leases and utilization fees from Hawthorne Airport in Southern California, which it acquired as a hub and test site last November.

Today’s Change
(-3.66%) $-0.20
Current Price
$5.27
Key Data Points
Market Cap
Day’s Range
$5.25 – $5.51
52wk Range
$4.30 – $14.62
Volume
13.3M
Avg Vol
34.7M
Gross Margin
-39275.36%
But is Archer actually cheaper relative to its long-term growth potential?
The FAA certification process consists of five stages. Joby has already reached the fifth stage, while Archer has just completed the third stage.
Therefore, Joby could launch its first commercial flights in the U.S. before Archer. However, Archer’s business could expand faster than Joby’s — albeit at lower margins — because it’s an OEM that will sell its Midnight eVTOLs to other companies. Joby will primarily use its S4 eVTOLs on its own air-taxi network, which will be integrated with Uber’s platform.
Both companies have big manufacturing partners. Toyota backs Joby, and Stellantis supports Archer. However, Joby’s partnership with Toyota is deeper and more structurally symbiotic than Stellantis’ investment-driven deal with Joby.
By 2028, analysts expect Joby’s revenue to reach $434.8 million. At its current market cap, it’s valued at 14 times that estimate. But Archer’s revenue is expected to reach $511.5 million by 2028 — and it trades at just eight times that estimate. So while Archer looks more expensive than Joby today, that balance could shift over the next few years as it ramps up its production.
That said, I still think Joby is a better all-around eVTOL stock than Archer for three reasons. First, the S4’s single tilt-rotor propellers make it faster and more energy-efficient than the Midnight. Second, Joby’s vertically integrated business will generate higher margins than Archer’s OEM business. Lastly, it’s further ahead of Archer in the FAA certification race.